


- Revenue rose 6.2% yoy to S$441.5 million, driven by new store openings.
- Gross profit margin improved 0.7 percentage points yoy to 32.2% due to a better sales mix.
- The Group opened three stores in 3Q FY2026, bringing the total number of new stores opened in 9M FY2026 to seven.
Singapore, 29 October 2026 – Sheng Siong Group Ltd. (“Sheng Siong”, together with its subsidiaries, the “Group” or “昇菘集团”), one of the largest supermarket chains in Singapore, reported a net profit of S$44.6 million for the 3 months ended 30 Sep 2026 (“3Q FY2026”), an increase of 1.8% year-on-year (“yoy”).
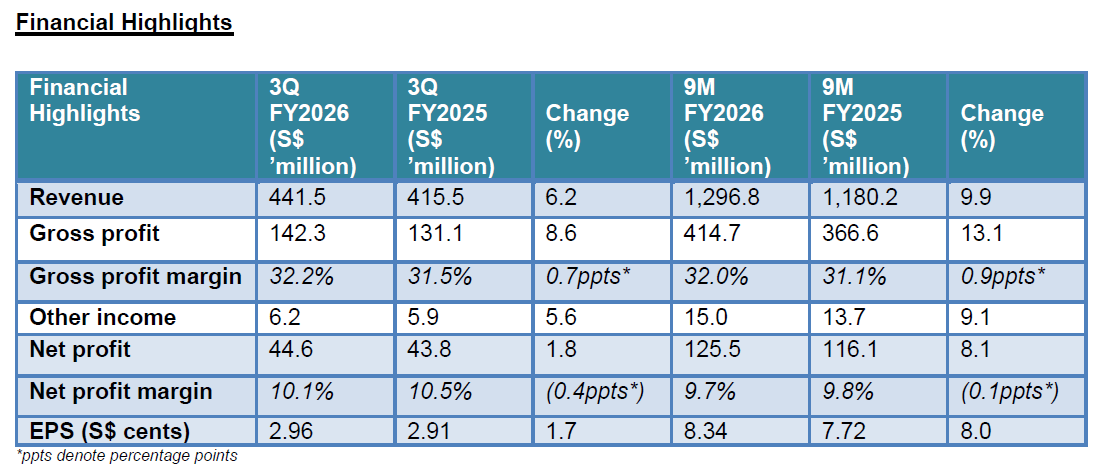
Revenue for 3Q FY2026 increased by 6.2% yoy to S$441.5 million, up from S$415.5 million in 3Q FY2025. This growth was primarily driven by the net increase in total stores in Singapore to 92, up from 84 in the same period last year. Revenue growth moderated in 3Q FY2026 against a high base in 3Q FY2025, when sales were lifted by the distribution of SG60 vouchers in July 2025. Gross profit increased by 8.6% yoy to S$142.3 million in 3Q FY2026. The Group’s gross profit margin improved by 0.7 percentage points to 32.2%, mainly attributed to continual improvements in the sales mix which helped offset higher operating costs.
Other income for 3Q FY2026 increased by 5.6% yoy to S$6.2 million, mainly due to higher miscellaneous income from a one-off recognition of rebates received from suppliers.
Administrative expenses rose by 12.1% yoy to S$18.0 million in 3Q FY2026, while selling and distribution expenses increased by 11.4% yoy to S$77.2 million. These are primarily due to the increased number of employees to support the opening of new stores and higher variable bonuses resulting from the Group’s better financial performance. In addition, higher depreciation of the right-of-use assets from new supermarket leases entered in 9M FY2026 and FY2025, as well as higher merchant fees from more sales settled through fee-incurring digital payment channels and the Group’s quick commerce business, also contributed to the increase in expenses.
Cash flow generated from operating activities for 3Q FY2026 decreased by 25.9% yoy to S$66.0 million, mainly due to earlier settlements to vendors. The Group ended the quarter with a cash and cash equivalents balance of S$388.9 million as of 30 September 2026.
Looking Forward
The Group expects grocery demand to remain resilient, supported by Singapore’s steady domestic economy, which grew 5.4% year-on-year in 3Q 20261, while core inflation rose to 2.2% in August from 2.0% in July2. The Retail Sales Index rose 1.3% and 0.7% year-on-year in July and August respectively, while the Supermarkets & Hypermarkets segment declined 2.6% in July before rising 1.6% in August3.
External risks, however, persist. Geopolitical uncertainties, global trade conditions and supply chain disruptions, together with extreme weather events and volatile energy prices, may affect food supplies and procurement costs. Against this backdrop, consumers are expected to remain value-conscious amid elevated living costs, and Sheng Siong’s value-for-money proposition, supported by competitively priced groceries and house brand products, positions the Group well to meet their everyday needs. However, the grocery retail landscape remains competitive, and sustained promotions could pressure revenue and margins.
The Johor Bahru–Singapore Rapid Transit System Link, now expected to commence passenger service in February 2027, may encourage more cross-border shopping and intensify price competition, particularly for selected packaged groceries and household products. However, the actual impact remains uncertain, and the Group believes that convenience, proximity and the availability of fresh produce will remain important drivers of everyday grocery purchases, supported by its extensive neighbourhood store network. The Group will adapt its strategies as developments unfold.
At the same time, wage increases under the Progressive Wage Model, higher transport costs due to higher diesel prices continue to keep operating costs elevated, with potential increases in electricity costs upon the renewal of energy supply contracts. Investments in AI capabilities and evolving sustainability and regulatory requirements may also increase operating expenses moving forward.
In light of these developments, the Group remains cautiously optimistic and will continue to strengthen its supply chain, optimise its sales mix, and enhance operational resilience and productivity through investments in automation and technology.
Mr Lim Hock Chee, the Group’s Chief Executive Officer, said, “The Group’s results over the recent quarters reflect our resilience amid rising business costs and a competitive operating environment. In June, we commenced our partnership with Foodpanda to strengthen our online retail presence, while our new Sungei Kadut distribution centre, designed to support more than 120 supermarkets, will underpin our continued expansion.
The Group opened three stores in 3Q FY2026 at Blk 181 Hougang Street 13, 11 Rivervale Crescent and Blk 905 Woodlands Avenue 5, raising the total number of new stores opened in 2026 to seven, and the store count in Singapore to 92. Looking ahead, we will continue to prioritise expansion in areas where the Group has limited presence, to extend our reach to customers.
The Group will also continue to enhance operational efficiency and maintain prudent cost management to navigate operational pressures.”
– End –
[1] Source: https://www.meti.gov.sg/newsroom/singapore-s-gdp-grew-by-5-4-per-cent-in-the-third-quarter-of-2026/
[2] Source: https://www.mti.gov.sg/newsroom/consumer-price-developments-in-august-2026-/
[3] Source: https://www.singstat.gov.sg


